How RSUs, ISOs, NSOs, and ESPPs Are Taxed
Understanding The Impact of Equity Compensation on Your Taxes
Stock compensation plans of various types are a common method of compensation for valued employees of successful companies. Generally, these plans come in the form of Restricted Stock or Restricted Stock Units (RSUs), Incentive Stock Options, Non-Qualified Stock Options, or Employee Stock Purchase Plans. Receiving these corporate benefits is excellent for wealth accumulation, but it’s essential to understand how taxes are generated from these sources of income.
Definitions
There are a number of terms pertaining to stock compensation that are important to know in order to understand the taxation. We will outline these below.
Grant Date
The date on which a company awards equity compensation to an employee.
Vesting Date
The date on which an employee gains the right to exercise stock options or receives shares of restricted stock.
Exercise Date
The date on which an employee exercises stock options to purchase company stock.
Vesting Schedule
The timeline that determines when portions of an equity grant vest, often in equal installments over several years.
Offering Period
The period during which an employee contributes to an ESPP through payroll deductions before shares are purchased.
Strike Price (Exercise Price)
The fixed price per share at which an employee can purchase company stock under a stock option, generally set at the stock’s market value on the grant date.
Expiration Date
The last date on which a stock option can be exercised before it is forfeited, commonly ten years after the grant date.
Cost Basis
The value used to calculate a gain or loss when shares are sold. For RSUs and NSOs, this generally includes the amount already taxed as income.
Restricted Stock & Restricted Stock Units (RSUs)
Restricted Stock and RSUs are one of the most common forms of equity compensation for employees. They are largely similar, but do have a few key differences.
Employees are granted shares or units of stock that are on “Restriction” for a period of time. As long as the conditions for vesting are met, the employee receives the stock on a pre-determined vesting date. This vesting date is also when the employee realizes income from receipt of the shares.
While employers usually withhold for taxes on the income accrued to the employee at the vesting event, they typically do not adequately withhold, which can lead to an unexpected tax bill come tax time. The market value of the shares determines the taxable income on the vesting date. Usually, the employer will immediately sell a portion of the shares upon vesting to cover the tax bill they create.
It is important to note that for post-vesting gains on Restricted Stock or RSU shares to qualify for taxation at the preferential capital gains tax rate, they must be held for one year after the vesting date.
Additionally, dividends paid by Restricted Stock during the restriction period are eligible for qualified dividend tax treatment, but RSU dividends paid are technically classified as “dividend equivalents” before vesting and are taxed as ordinary income. Finally, the complex 83(b) election outlined later in this article is only available for Restricted Stock, not RSUs.
Example: How Restricted Stock & RSUs Are Taxed
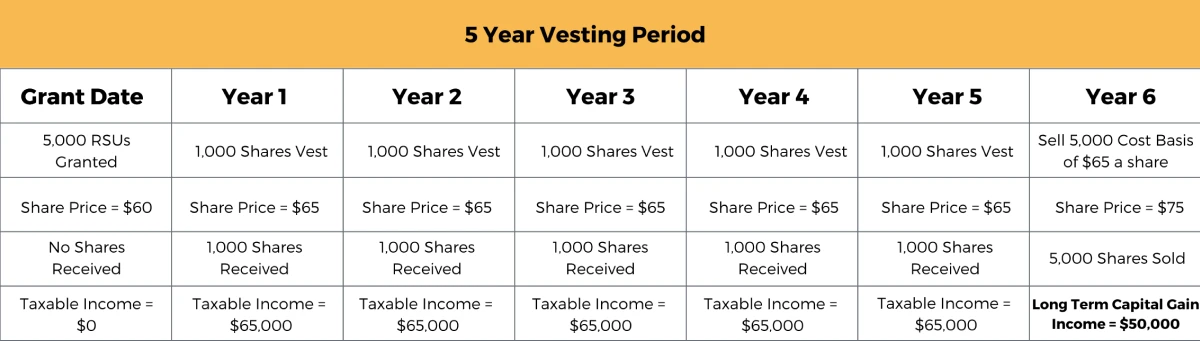
Let’s say that Julian is granted 5,000 RSUs that vest at a rate of 20% annually, and the market price at the grant date is $60 a share. The stock price the next year is $65. This means that in the first year of the stock vesting, Julian will show and be taxed on a $65,000 vesting event (1,000 Shares x $65 vest price). This amount will be shown on his W-2 box 1 wage.
Let’s say the stock price stays at $65 for the remaining vesting schedule. This means that for five years in a row, Julian will show an additional $65,000 of income on his W-2 but not actually receive cash for the income (this is why many people immediately sell some shares to cover the tax liability and diversify the stock grant).
If in year six Julian sells all 5,000 of the shares when the share price is $75 a share, he will recognize a $50,000 long-term capital gain (Cost Basis of 5,000*$65 = $325,000 sell price of 5,000*$75 = $375,000). Please see Exhibit 1 below for a visualization of this example.
As previously mentioned, there are a couple of key differences Between RSUs and Restricted Stock, sometimes also known as Restricted Stock Awards (RSAs). RSAs are eligible for the 83(b) election, which is a tax planning tool that allows a Restricted Stock recipient to set their cost basis and holding period at the grant price and date. This election realizes the taxable income at grant, not vesting, and can be an excellent strategy.
However, there are a few pitfalls to be aware of prior to making the 83(b) election. For more information regarding Restricted Stock, RSAs, and the 83(b) election, please see Understanding the 83(b) Election and Restricted Stock.
Incentive Stock Options (ISOs) & Non-Qualified Stock Options (NSOs/NQSOs)
Stock option compensation for employees tends to be more complex in nature. There are two primary types of option compensation: ISOs and NSOs (Sometimes referred to as NQSOs). The difference comes down to the tax treatment of the stock at exercise of the option and subsequent liquidation of the stock.
ISO Tax Treatment
An ISO is a right an employer gives an employee to buy stock in the company at a later date for a price equal to or more than the stock’s market value at the time of the initial agreement.
There are holding period requirements that must be met before ISOs can be sold at the preferential capital gains tax rates. If an ISO is not held for more than a year past the exercise date and two years from the grant date, the net benefit to the employee from the stock option will be subject to ordinary income tax rates.
It is important to note that ISOs must be exercised within 90 days after employment ends (one year in the case of disability) to keep their favorable tax treatment. Options exercised after that window are taxed as NSOs. Many plans also cancel vested options shortly after departure, so an employee who leaves a company may need to act quickly. Plan documents should be reviewed before any departure date is set.
Unlike NSOs, there is no tax when the options are exercised with ISOs. Tax is only realized when the stock is sold – and if the conditions are met, only at capital gains tax rates.
There is also an Alternative Minimum Tax (AMT) implication to consider with ISOs. The spread between the stock’s fair market value at exercise and the option’s strike price is not subject to regular income tax until the shares are sold. However, that spread is added to income for AMT purposes in the year of exercise. Whether an employee actually owes AMT depends on total income and the size of the exercise.
Under the One Big Beautiful Bill Act (OBBBA), starting in 2026 the AMT exemption begins to phase out at $500,000 of AMT income for single filers and $1,000,000 for joint filers, and it phases out twice as fast as it did before. As a result, a large ISO exercise can trigger AMT even for employees who have never paid it in the past. The good news is that AMT paid on an ISO exercise can often be recovered as a credit in future years.
Example: How ISOs Are Taxed
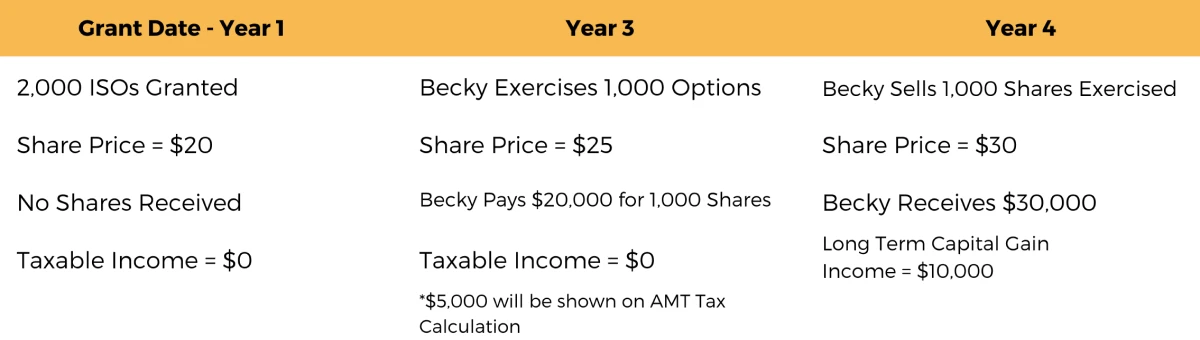
Let’s say Becky is granted an ISO to purchase 2,000 shares of her company’s stock at the current market price of $20. The option vests two years after the ISO was granted to Becky when her company’s stock price has risen to $25 a share.
Becky then exercises 1,000 of the stock options and purchases 1,000 shares of the stock for $20,000 (1,000*20).
That year on Becky’s tax return she will need to show a $5,000 gain for AMT purposes (1,000*25 = 25,000 minus 1,000*20 = 20,000). After Becky has held the stock for a year, she sells it when the price is $30 a share, and she will show a long-term capital gain of $10,000 (1,000*$30 = $30,000 minus 1,000*$20 = $20,000).
This is the most tax-efficient way for Becky to exercise her options. If Becky were to sell the shares before she held them for one year after exercising her options, then the $10,000 will be counted as ordinary income to her and taxed at a higher tax rate.
Please see exhibit 2 below for a visualization of this example.
NSO Tax Treatment
Non-Qualified Stock Options (NSOs) are a more common form of compensation than ISOs. Additionally, the tax implication of this compensation is far less complex. NSOs, like ISOs, give an employee the right to purchase a set number of shares within a designated timeframe at a predetermined price. Like ISOs, the predetermined price must be the same as or greater than the market price on the grant date of the NSOs.
The difference in taxation between ISOs and NSOs comes into play when the stock options are exercised. The difference between the exercise price of the option and the current price of the stock is known as the “Bargain Element”, which is fully taxable as ordinary income and subject to payroll taxes for both the employee and employer.
Example: How NSOs Are Taxed
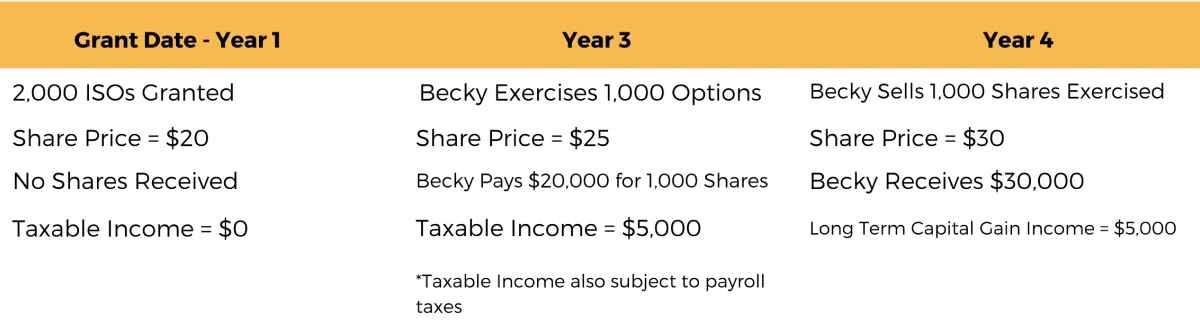
Let’s revisit Becky’s example and assume that instead of her options being qualified ISOs, they were NSOs. This means that at the grant date, ISOs and NSOs look identical.
Then, in year 3 when Becky exercises 1,000 shares for $20 a share when the market price is $25 a share, she will have to pay taxes on the $5,000 appreciation (1,000*$25 = $25,000 minus 1,000*$20 = $20,000). This $5,000 appreciation will be shown on Becky’s W-2. Please see exhibit 3 below for a visualization of this example.
Employee Stock Purchase Plans (ESPPs)
ESPPs are taxed similarly to ISOs. The IRS mandates that no more than $25,000 of stock may be purchased annually, and the employer can only give a maximum of 15% discount on the stock.
They have the same holding period requirements as ISOs in that they must be held for more than one year after purchase and more than two years after the offering date. The “Bargain Element,” or discount the employee received, is always taxed as ordinary income. However, if both holding period requirements are met, any appreciation above that discount receives preferential long-term capital gains treatment.
Phantom Stock and Stock Appreciation Rights (SARs)
Another intangible form of equity-based compensation is Phantom Stock or Stock Appreciation Rights. Unlike Restricted Stock or Stock Options, neither of these options result in the employee owning the stock (with the exception of stock-settled SARs) – they simply receive a cash value tied to the stock price. In the case of Phantom Stock, the employee receives the cash value of the “Phantom Shares” rather than the shares of stock.
Similarly for SARs, the employee receives cash when they exercise the “appreciation right” for the difference between the stock price at exercise and the strike price listed on the STAR when granted to the employee. The net cash value for both of these plans is taxed as ordinary income when delivered to the employee.
Both of these equity compensation options have certain advantages. For the employee, they simply receive cash value rather than having to purchase or sell stock post-transaction. For the employer, these methods still incentivize the employee to pursue strong company performance, since the stock value appreciating increases the value of the Phantom Shares and SARs. However, the company does not have to utilize treasury stock or authorize real shares of stock to be distributed, which makes administration of these plans somewhat easier.
FAQs
Below are some frequently asked questions surrounding the taxation of stock compensation.
Why do I owe taxes on my RSUs when my employer already withheld?
Most employers withhold federal tax on RSU income at the flat supplemental rate of 22% (37% on supplemental wages above $1 million in a year). If your income puts you in the 32%, 35%, or 37% bracket, that withholding falls short, and you owe the difference when you file. For large vests, consider talking with a tax professional to ensure adequate withholding.
Are RSUs taxed twice?
They should not be, but it often happens by mistake. The value of your shares at vesting is already included in your W-2 income. When you later sell, your broker may report a cost basis of zero or leave it blank on Form 1099-B. If you file that form as-is, you pay tax on the same income a second time. The fix is to report the correct cost basis (the value at vesting) on Form 8949. The same issue applies to shares from exercised NSOs.
What is the difference between ISOs and NSOs for taxes?
Both let you buy company stock at a fixed price. With NSOs, the spread at exercise is taxed as ordinary income on your W-2 and is subject to payroll taxes. With ISOs, there is no regular income tax at exercise, but the spread counts toward the Alternative Minimum Tax. If you hold ISO shares more than two years from grant and more than one year from exercise, the entire gain is taxed at long-term capital gains rates.
Conclusion
Although this article covers the most common equity compensation programs, employers may use other plan types and variations. Each one comes with its own tax rules, and the decisions around when to exercise, when to sell, and how much company stock to hold can have a lasting effect on an employee’s after-tax wealth. With the AMT changes under the One Big Beautiful Bill Act taking effect in 2026, careful planning around these plans is more important than ever. For employees whose compensation is heavily tied to company stock, coordinating these decisions with a broader tax and retirement plan can make a significant difference over time.
Need Some Help?
If you’d like some help from one of our CPAs or CERTIFIED FINANCIAL PLANNER (CFP®) advisors, the Rhame & Gorrell Wealth Management team is here to help.
Our experienced Wealth Managers facilitate our entire suite of services including financial planning, investment management, tax optimization, estate planning, and more to our valued clients.
Feel free to contact us at (832) 789-1100, [email protected], or click the button below to schedule your complimentary consultation today.
IMPORTANT DISCLOSURES:
Corporate benefits may change at any point in time. Be sure to consult with human resources and review Summary Plan Description(s) before implementing any strategy discussed herein.Rhame & Gorrell Wealth Management, LLC (“RGWM”) is an SEC registered investment adviser with its principal place of business in the State of Texas. Registration as an investment adviser is not an endorsement by securities regulators and does not imply that RGWM has attained a certain level of skill, training, or ability. This material has been prepared for informational purposes only, and is not intended to provide, and should not be relied on for, tax, legal or accounting advice. You should consult your own CPA or tax professional before engaging in any transaction. The effectiveness of any of the strategies described will depend on your individual situation and should not be construed as personalized investment advice. Past performance may not be indicative of future results and does not guarantee future positive returns.
For additional information about RGWM, including fees and services, send for our Firm Disclosure Brochures as set forth on Form ADV Part 2A and Part 3 by contacting the Firm directly. You can also access our Firm Brochures at www.adviserinfo.sec.gov. Please read the disclosure brochures carefully before you invest or send money.