The Backdoor Roth IRA: Benefits, Rules, and How To Set One Up
How High Earners Can Still Fund a Roth IRA in 2026
The Backdoor Roth IRA is a two-step strategy that allows individuals whose income exceeds the IRS limits to accumulate Roth IRA assets. Under this strategy, an individual makes a nondeductible contribution to a Traditional IRA and subsequently converts those funds to a Roth IRA. Once converted, the assets may grow and be withdrawn tax-free in retirement, provided certain requirements are met.
Lawmakers have proposed eliminating this strategy on several occasions. Most notably, the Build Back Better Act of 2021 passed the House of Representatives with provisions that would have ended it, but the bill did not advance in the Senate. Neither the SECURE 2.0 Act of 2022 nor the One Big Beautiful Bill Act of 2025 imposed any restrictions. As of 2026, the Backdoor Roth IRA continues to be a viable strategy.
Although the mechanics are straightforward, several rules can cause a portion of the conversion to become taxable. The sections below address how the strategy works, the individuals for whom it is most appropriate, and the potential issues to consider before implementing it.
Traditional vs. Roth IRA
An Individual Retirement Arrangement (IRA) is a tax-advantaged account that individuals may use to save and invest for retirement. The two primary types are the Traditional IRA and the Roth IRA. The principal difference between them is when income tax is paid.
- Traditional IRA: Contributions may be tax-deductible, depending on the individual’s income and whether they are covered by a workplace retirement plan. Investment growth is tax-deferred, and withdrawals are taxed as ordinary income.
- Roth IRA: Contributions are made with after-tax dollars and are not deductible. Investment growth is tax-free, and qualified withdrawals are not subject to income tax.
For 2026, an individual may contribute up to $7,500 across all Traditional and Roth IRAs combined, or $8,600 for those age 50 or older.
A married individual filing a joint return may also contribute to an IRA on behalf of a spouse with little or no earned income. This is commonly referred to as a Spousal IRA. It allows a household to contribute up to $15,000 for 2026, or $17,200 if both spouses are age 50 or older.
For a more detailed comparison of the two account types, please see our Traditional vs. Roth IRA article.

IRA Contribution Phase-Outs
Both IRA types are subject to income limits, though the limits apply in different ways.
Traditional IRA deductibility
There is no income limit on contributions to a Traditional IRA. However, if an individual or their spouse is covered by a workplace retirement plan, the ability to deduct the contribution phases out as modified adjusted gross income (MAGI) rises. A contribution that cannot be deducted may still be made as a nondeductible contribution. Nondeductible contributions create after-tax basis in the account, which is central to the Backdoor Roth IRA strategy.
Roth IRA eligibility
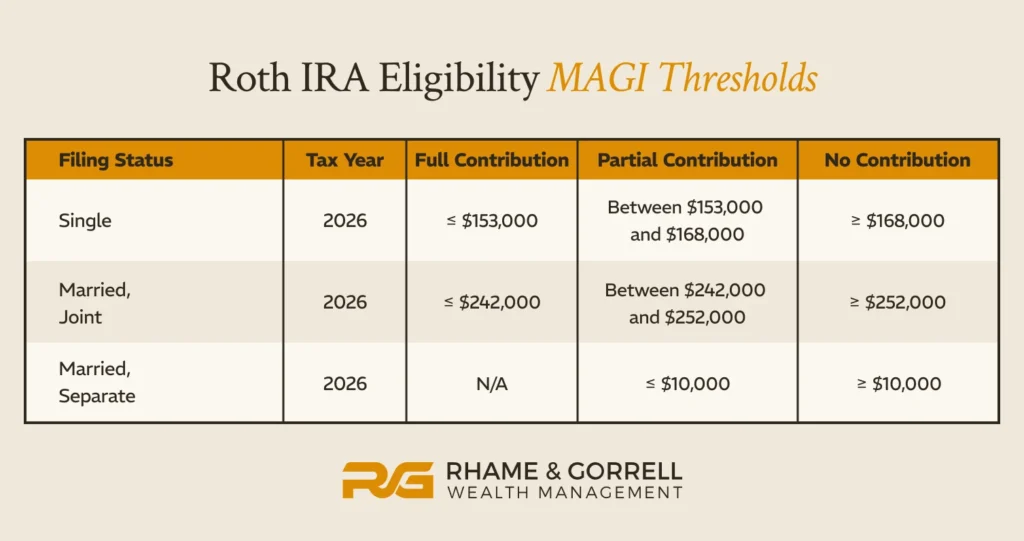
Direct contributions to a Roth IRA are limited by MAGI, whether or not the individual is covered by a workplace plan. Within the phase-out range, the allowable contribution is reduced. Above the range, no direct contribution is permitted.
Roth IRA Eligibility MAGI Thresholds
How much you can contribute directly to a Roth IRA depends on your filing status and modified adjusted gross income (MAGI). Hover or tap a cell for detail.
How Does a Backdoor Roth IRA Work?
Before 2010, individuals with MAGI above $100,000 were not permitted to convert a Traditional IRA to a Roth IRA. The Tax Increase Prevention and Reconciliation Act of 2005 removed this restriction beginning in 2010. Since then, any taxpayer may convert Traditional IRA assets to a Roth IRA, regardless of income.
The Backdoor Roth IRA combines two rules: there is no income limit on Traditional IRA contributions, and there is no income limit on Roth conversions. An individual who is ineligible to contribute to a Roth IRA directly may make a nondeductible contribution to a Traditional IRA and then convert those funds to a Roth IRA.
A Roth conversion can be a taxable event, but only to the extent that the converted amount consists of pre-tax dollars. A nondeductible contribution is made with after-tax dollars, so converting it generally produces little or no tax. There are two exceptions that apply. First, any earnings that accrue before the conversion are taxable. Second, if the individual holds pre-tax funds in any Traditional, SEP, or SIMPLE IRA, a portion of the conversion will be taxable under the Pro Rata Rule, discussed in detail below and in our article on the Pro Rata Rule.

Who Should Consider a Backdoor Roth IRA?
This strategy is most appropriate for individuals whose income exceeds the Roth IRA phase-out range for their filing status. For 2026, direct Roth IRA contributions are fully phased out at MAGI above:
- $168,000 for single and head of household filers
- $252,000 for married couples filing jointly
Individuals whose MAGI falls within the phase-out range may make only a reduced direct contribution. Many in this position elect to use the Backdoor Roth IRA for the full amount instead. This approach removes the need to calculate a reduced contribution and avoids the risk of an excess contribution if income ends up higher than expected. That risk is common for individuals who receive annual bonuses or equity compensation, where final income is often not known until year-end. An excess contribution that is not corrected is subject to a 6% penalty for each year it remains in the account.
Can You Contribute Directly to a Roth IRA?
Roth IRA contributions phase out at higher incomes. Choose a filing status and drag to your modified adjusted gross income (MAGI).
The strategy is generally most efficient for individuals who hold no pre-tax balances in Traditional, SEP, SIMPLE, or rollover IRAs, or who are able to roll those balances into a current employer’s retirement plan. Those with significant pre-tax IRA balances that cannot be moved should evaluate the strategy carefully, as the Pro Rata Rule may cause a large portion of each conversion to be taxable.
Important Considerations for This Strategy
Although the Backdoor Roth IRA is well established, several rules require careful attention. An error in any of these areas can create an unexpected tax liability.
The Pro Rata Rule and IRA Aggregation
For purposes of calculating the tax on a conversion, the IRS treats all of an individual’s Traditional, SEP, SIMPLE, and rollover IRAs as a single account. The taxable portion of any conversion is based on the ratio of pre-tax dollars to total dollars across all of these accounts, regardless of which account the conversion comes from. Roth IRAs, inherited IRAs, a spouse’s IRAs, and balances held in employer retirement plans such as a 401(k) are not included in this calculation.
For example, assume an individual holds $92,500 in a rollover IRA funded entirely with pre-tax dollars. The individual then makes a $7,500 nondeductible contribution to a new Traditional IRA and converts it. Pre-tax dollars represent 92.5% of the combined $100,000 balance, so approximately $6,938 of the $7,500 conversion would be taxable.
The calculation uses IRA balances as of December 31 of the year in which the conversion occurs. An individual with pre-tax IRA balances may be able to avoid this outcome by rolling those balances into a current employer’s retirement plan before year-end. Not all employer plans accept incoming rollovers, so the plan’s rules should be confirmed in advance.
Form 8606
Form 8606 must be filed with the federal tax return for any year in which an individual makes a nondeductible contribution or completes a Roth conversion. The form records the individual’s after-tax basis and determines the taxable portion of the conversion. Each spouse who completes a Backdoor Roth IRA files a separate Form 8606. Failing to file the form can result in a penalty and may cause the after-tax contribution to be taxed a second time upon conversion.
Five-Year Rules
Roth IRAs are subject to two separate five-year rules. Earnings in a Roth IRA may be withdrawn tax-free only after the individual has reached age 59½ and the account owner’s first Roth IRA has been open for at least five years. In addition, any portion of a conversion that was taxable is subject to its own five-year period, and a withdrawal of that amount before age 59½ and before the period ends may incur a 10% penalty. These rules rarely affect long-term savers but should be considered by anyone who may need the funds before retirement.
The Step-Transaction Doctrine
The step-transaction doctrine is a legal principle under which a series of related steps may be treated as a single transaction for tax purposes. Applied here, the concern is that the IRS could view a nondeductible contribution followed by an immediate conversion as a direct Roth IRA contribution, which the individual was not eligible to make. Congress addressed this in the conference report for the Tax Cuts and Jobs Act of 2017, which acknowledged that individuals above the income limits may contribute to a Traditional IRA and convert those funds to a Roth IRA. Some advisors nonetheless recommend allowing time between the contribution and the conversion, although no waiting period is required.
Conclusion
The Roth IRA is among the most tax-advantaged accounts available to individual investors. Assets grow tax-free, and qualified withdrawals are not subject to income tax. These withdrawals are also excluded from the income used to determine Medicare premium surcharges and the 3.8% Net Investment Income Tax, and the account is not subject to required minimum distributions during the owner’s lifetime.
For individuals whose income exceeds the Roth IRA limits, the Backdoor Roth IRA provides a reliable path to building Roth assets. Over time, consistent annual contributions can grow into a meaningful source of tax-free retirement income, providing greater flexibility in retirement. The strategy is most effective when existing pre-tax IRA balances, contribution timing, and tax reporting are addressed in advance. Individuals should review their circumstances with a qualified financial or tax professional before proceeding.
At Rhame & Gorrell, our CPAs and CFP® professionals help clients complete the Backdoor Roth IRA each year, coordinate the associated Form 8606 filings, and incorporate it into a broader Roth conversion plan that addresses the timing and size of conversions leading into and throughout retirement. To discuss whether the Backdoor Roth IRA is appropriate for you, schedule a complimentary consultation with our team today.
Downloadable Resources:
Need Some Help?
If you’d like some help from one of our CPAs or CERTIFIED FINANCIAL PLANNER (CFP®) advisors regarding this strategy and how it applies to you, the Rhame & Gorrell Wealth Management team is here to help.
Our experienced Wealth Managers facilitate our entire suite of services including financial planning, investment management, tax optimization, estate planning, and more to our valued clients.
Feel free to contact us at (832) 789-1100, [email protected], or click the button below to schedule your complimentary consultation today.
IMPORTANT DISCLOSURES:
Corporate benefits may change at any point in time. Be sure to consult with human resources and review Summary Plan Description(s) before implementing any strategy discussed herein.Rhame & Gorrell Wealth Management, LLC (“RGWM”) is an SEC registered investment adviser with its principal place of business in the State of Texas. Registration as an investment adviser is not an endorsement by securities regulators and does not imply that RGWM has attained a certain level of skill, training, or ability. This material has been prepared for informational purposes only, and is not intended to provide, and should not be relied on for, tax, legal or accounting advice. You should consult your own CPA or tax professional before engaging in any transaction. The effectiveness of any of the strategies described will depend on your individual situation and should not be construed as personalized investment advice. Past performance may not be indicative of future results and does not guarantee future positive returns.
For additional information about RGWM, including fees and services, send for our Firm Disclosure Brochures as set forth on Form ADV Part 2A and Part 3 by contacting the Firm directly. You can also access our Firm Brochures at www.adviserinfo.sec.gov. Please read the disclosure brochures carefully before you invest or send money.